Chapter Seven · Plan for Your Money
Freedom & Legacy
Calculator
Ask your 65-year-old self how much he wants to live on each year. Ask your 55-year-old self whether he wants the option to step away early. Once you choose those two numbers, everything else is math.
The future you're funding
Choose the income you want in each phase. The math tells you what it costs.
The decade where work becomes optional instead of necessary.
Ideally tax-free, funded through Roth accounts.
Brokerage account, broad index funds.
Roth IRA or Roth 401(k). The 2026 Roth IRA limit is $7,500 for those under 50. Limits and income phase-outs change annually — last checked September 2026.
7.5% is the figure used throughout Chapter 7.
To fund that future, invest
$20,444 / year
That's $1,704 a month, starting now.
What waiting costs
Same future. Same target income. You just start later.
Email me my numbers
We'll send this to you so you can come back to it.
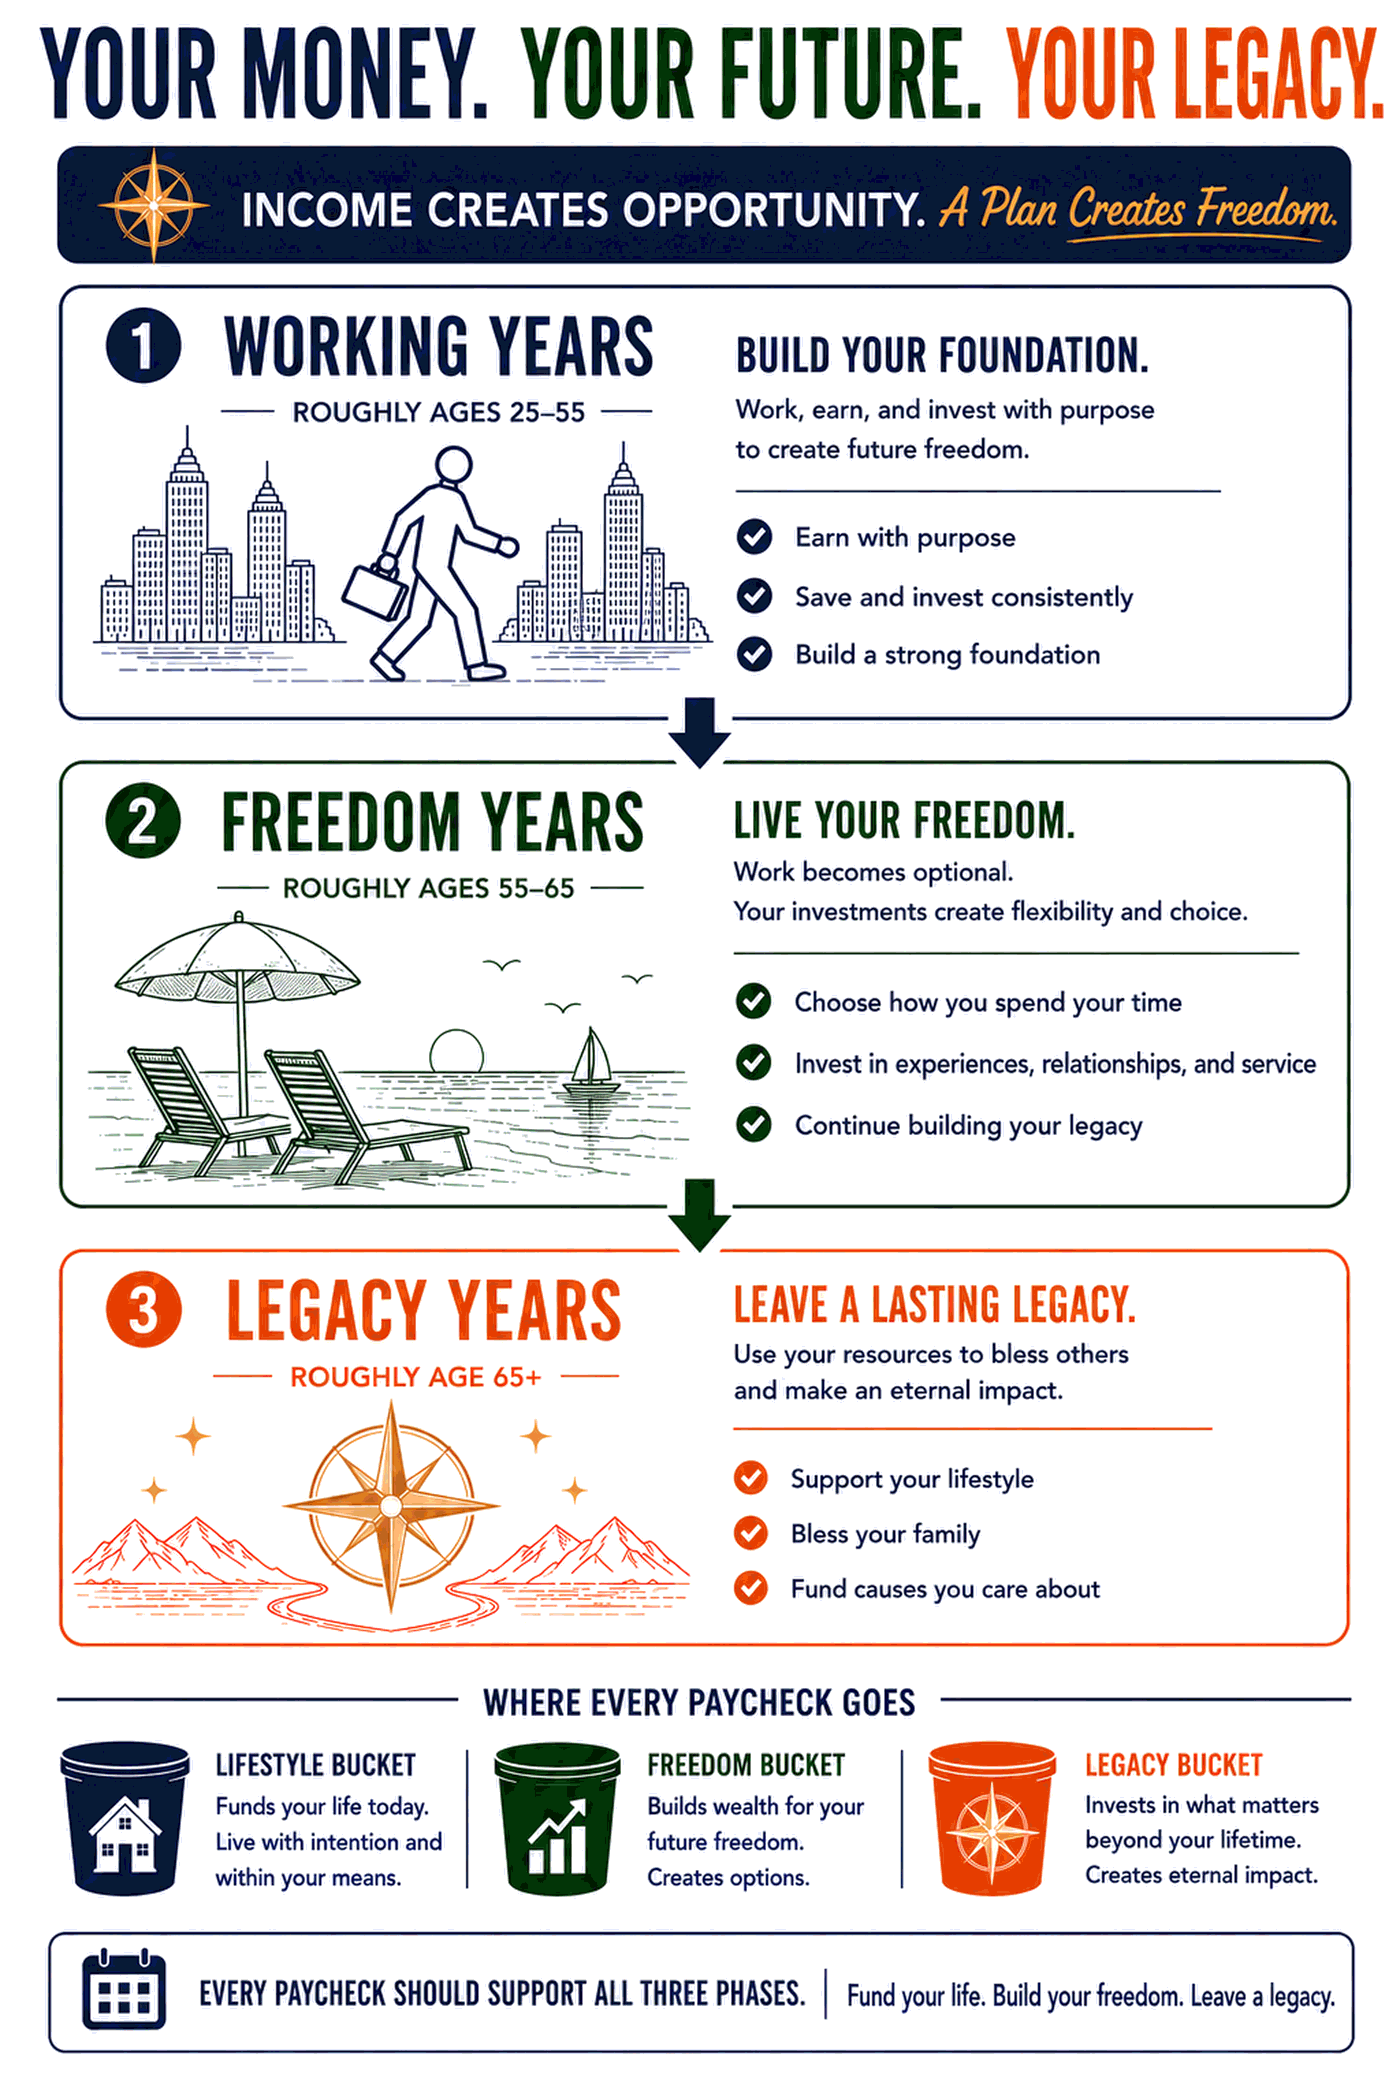
The three phases behind these numbers
Income creates opportunity. A plan creates freedom. Your working years are what make the other two possible.
Every figure here is shown in estimated future dollars and is not adjusted for inflation. They should not be read as having the same purchasing power as those amounts today. Before investing, confirm current eligibility and contribution rules. Ben Roberts is not a licensed financial advisor and nothing here is personalized investment advice. Talk to a licensed professional who knows your actual situation before making significant financial decisions.